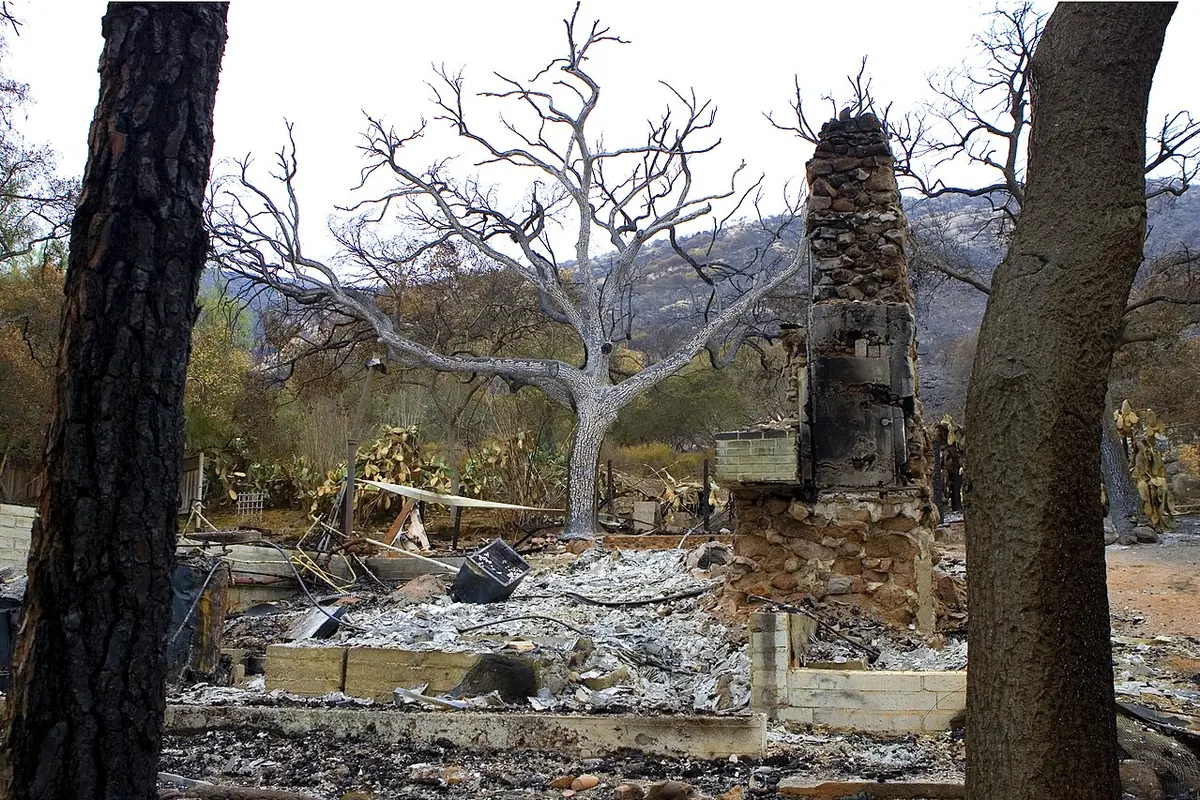
The first weeks after the fire
New Mexico knows wildfire. The Cerro Grande Fire in 2000 burned into Los Alamos, the Hermits Peak/Calf Canyon Fire in 2022 became the largest in the state’s recorded history, and the South Fork and Salt fires near Ruidoso in June 2024 destroyed homes in a matter of hours. If you have lost a home, you already know that the claim is the last thing you want to think about. It is also the thing that decides how you rebuild.
This guide is general. Every policy is different, and fire-specific programs or settlements may apply to some events. Read your own policy and ask questions before you sign anything.
Get organized before you get detailed
- Report the loss and write down your claim number and adjuster’s contact information.
- Ask for a complete copy of your policy, including the declarations page and every endorsement.
- Start one folder, paper or digital, for every letter, receipt and estimate.
- Keep a simple log of calls: date, who you spoke to and what was said.
The claim calendar builder helps you track dates that appear in your policy, such as proof of loss requests and repair deadlines.
Additional living expense
Coverage D, often called loss of use or additional living expense (ALE), pays the increase in your living costs while you can’t live at home. It is not a flat allowance. It typically covers the difference between what you normally spend and what you’re spending now: rent, extra mileage, laundry, pet boarding, higher utility bills.
- Save every receipt and submit them on a regular schedule.
- Ask in writing how long ALE will last and whether it is limited by dollars, time or both.
- If rentals are scarce after a large fire, document what you searched for and what it cost.
The contents inventory
Coverage C is usually the hardest part of a total loss. Insurers often ask for a room-by-room list of everything you owned, with age, quantity and replacement cost. That is a daunting request when the house is gone.
How to build it
- Walk through the house in your mind, room by room, closet by closet. Do it with family members, who remember different things.
- Use old photos, videos, social media posts and online order histories.
- Pull bank and credit card statements for larger purchases.
- Ask whether your policy pays contents at replacement cost or actual cash value, and whether any portion can be paid without an itemized list.
Our wildfire contents inventory estimator gives you a rough starting picture by room so you can see where the list may be thin.
Debris removal
Clearing a burned lot is expensive, and in a large disaster it may be handled through a government program, a private contractor or a mix. Debris removal coverage may sit inside your dwelling limit, carry its own additional amount, or both. Before a contractor starts, ask the carrier how debris removal will be paid and whether any program you join affects that.
Valuing the dwelling
A total loss estimate for the house should reflect the actual home: square footage, foundation, framing, stucco or adobe walls, roof type, interior finishes, and site work such as driveways and retaining walls. Common gaps include:
- Pricing that doesn’t reflect post-fire labor and material costs in your area.
- Missing ordinance or law costs for current code, which may require upgrades the old house didn’t have.
- Detached structures left off Coverage B, such as garages, coyote fences and wells.
- Smoke and heat damage to nearby structures that didn’t burn.
If your coverage limit seems far below what rebuilding will cost, an attorney can tell you whether any legal questions arise. An appraiser values the loss within the policy.
If your home survived but the neighborhood didn’t
Homes at the edge of a burn area often come through standing but full of smoke, ash and soot. Smoke damage claims can involve cleaning or replacing insulation, HVAC ductwork, evaporative cooler pads, soft furnishings and clothing, plus repainting and sealing. Ask for testing if odor lingers after cleaning, and keep records of any time you couldn’t safely live in the house, since that may support additional living expense.
Rebuild or buy elsewhere
Some families rebuild on the same lot. Others decide to buy an existing home somewhere else. Your policy’s loss settlement terms affect that choice. Some policies pay full replacement cost whether you rebuild on site or elsewhere; others limit what you can recover if you don’t rebuild, or require replacement within a stated time to release recoverable depreciation. Get the carrier’s answer in writing before you commit. If you need more time, ask for an extension in writing too.
When the numbers don’t line up
If the carrier accepts the loss but its estimate for the dwelling, contents or other structures is well below what the work will actually cost, the appraisal clause may help. Appraisal decides the amount of loss, not whether something is covered. We handle wildfire loss appraisal and fire and smoke damage appraisal, and we can start with a claim estimate review if you want a second opinion first.
Questions about claim handling can go to the New Mexico Office of Superintendent of Insurance, which takes consumer complaints. For legal questions, talk with a New Mexico attorney. When you’re ready, reach out and we’ll talk through where your claim stands.