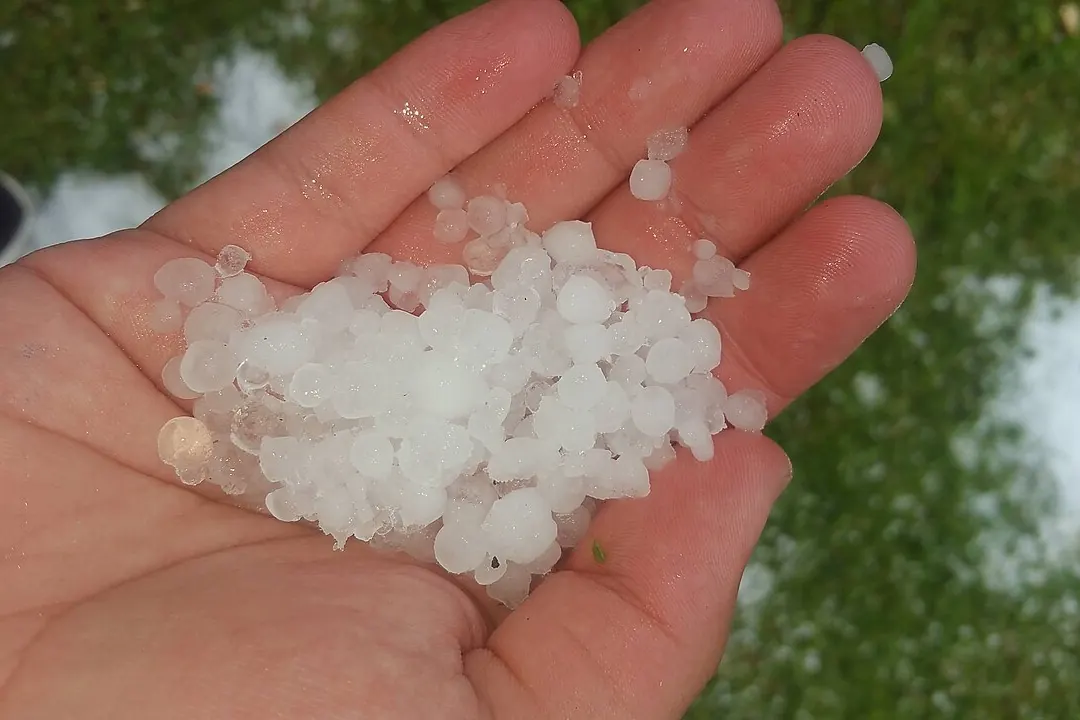
Why it matters for hail-belt policies
Insurers writing in hail-prone parts of New Mexico — the eastern plains, the Albuquerque metro and the Four Corners — sometimes use a separate wind/hail deductible set as a percentage of Coverage A. On a $320,000 dwelling limit, 2% is $6,400, not the $1,000 printed elsewhere on the declarations page.
Where to find yours
Check the declarations page for “wind/hail,” “windstorm or hail” or a percentage next to a deductible. Endorsements later in the policy explain when it applies.
What it means for appraisal
The deductible doesn’t change the amount of loss an appraisal panel sets, but it changes what you receive. A loss barely above the deductible may not justify appraisal fees; one far above it might.
Illustrative example: the default numbers are made up to show the calculation.
Questions about this estimator
Is the percentage taken from the claim or from my coverage?
Usually from the Coverage A dwelling limit, then applied to the whole wind or hail loss. Your policy wording controls.
Can I lower it?
Typically only at renewal, and a lower deductible usually costs more in premium.
Is anything I type saved or sent?
No. The tool runs entirely in your browser. Close the page and the numbers are gone.