- Monsoon hail
- Spring wind
- Flat-roof leaks
- Arroyo flash flooding
- Freeze-burst pipes
Why Albuquerque losses get disputed
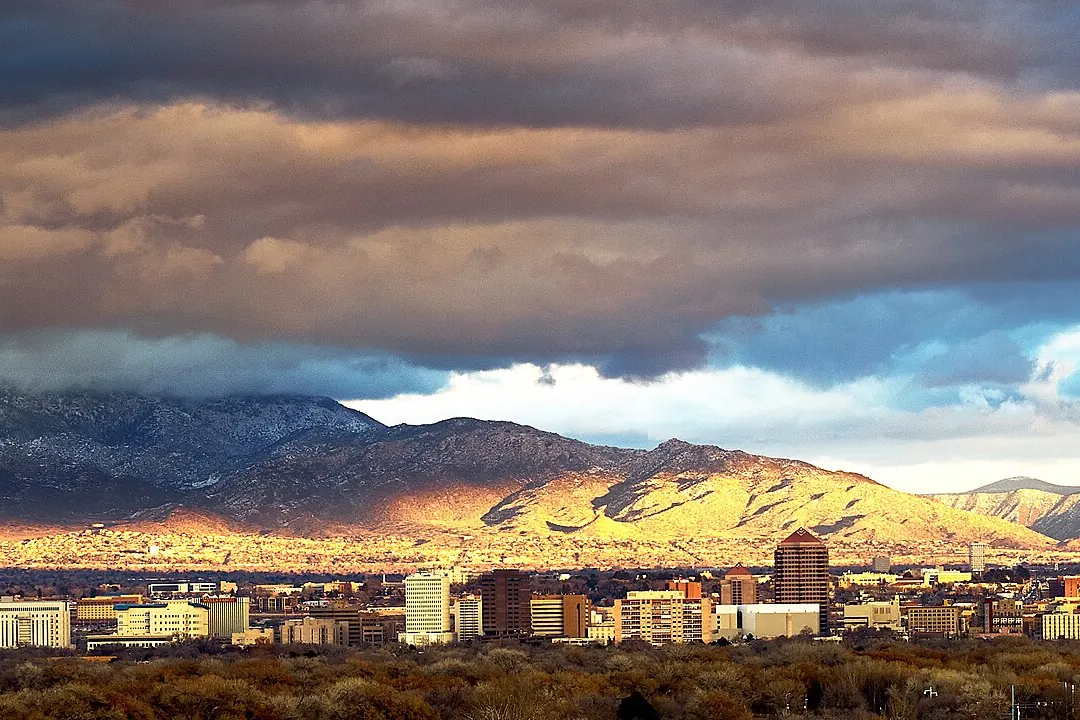
Bernalillo County sits in a wide basin between the Sandia Mountains and the West Mesa, and the weather arrives in two distinct acts. Spring brings long, dry wind events that peel shingles and drive grit into stucco. Then the summer monsoon, usually from early July into September, builds afternoon thunderstorms over the Sandias that can drop hail across the Northeast Heights in minutes and send water racing down arroyos toward the Valley. Add occasional hard freezes in winter, and a single house can collect several kinds of damage within a year.
That mix is exactly where disagreements start. An adjuster sees granule loss and calls it age; a roofer sees fresh bruising and calls it hail. A stucco crack gets written as settlement rather than impact. When both sides have a reasonable argument and the dollars are real, the appraisal clause in most New Mexico homeowners policies is built for this situation.
The housing stock, neighborhood by neighborhood
Older homes in Nob Hill and near the university mix Pueblo Revival flat roofs with Territorial brick coping and some of the city’s earliest pitched-roof cottages. In the North Valley and South Valley you’ll find genuine adobe and acequia-side properties where drainage and wall moisture complicate any water claim. The Northeast Heights are dominated by 1960s through 1990s stucco ranch homes, many with built-up or modified bitumen roofs behind short parapets and an evaporative cooler perched on top. Four Hills and Sandia Heights add foothill lots with more wind exposure and, on the edge of the open space, wildfire smoke concerns. Across the river, the Westside subdivisions are newer, mostly pitched concrete tile or architectural shingle over frame-and-stucco walls.
Claim disputes we see most in the metro
- Flat-roof hail. Low-slope membranes don’t show hail the way shingles do, so damage is often missed or written as “wear.” See our flat roof and stucco appraisal page.
- Stucco matching. Patching one elevation with a color coat that will never blend is a common line-item fight.
- Cooler and parapet damage. Bent cooler housings, split ducts and torn parapet caps are frequently left off the estimate.
- Water losses after a freeze. Pipe bursts in exterior walls and attics raise questions about sudden versus gradual damage. Our winter freeze appraisal page explains how we document them.
How we work in Albuquerque
We are an independent appraisal practice serving all of New Mexico rather than a storefront office. For an Albuquerque claim we start by reading the policy and the carrier’s estimate, then inspect the property and build our own line-by-line scope. If the gap is mostly pricing, a claim estimate review may settle it without invoking appraisal. If it isn’t, we serve as your appointed appraiser under the clause, and if the two appraisers can’t agree, the matter goes to an umpire. You can read the full sequence in inside the appraisal process.
Roof measurements matter on pitched Westside homes, so our roof area and pitch converter is a useful first check on the carrier’s square count. When you’re ready, reach out with your policy declarations and estimate.
Services available in Albuquerque
Every New Mexico Insurance Appraiser service is available in Albuquerque and the rest of Bernalillo County, including:
- Appraisal Clause Representation
- Home Insurance Appraisal
- Commercial & HOA Appraisal
- Hail & Roof Appraisal
- High Wind Damage Appraisal
- Water Damage Appraisal
- Fire & Smoke Damage Appraisal
- Wildfire Loss Appraisal
Albuquerque claim questions
Can hail damage a flat roof in the Northeast Heights even if I don’t see holes?
Yes. Hail can fracture membrane surfacing, crack aged coatings and loosen seams without leaving an obvious hole, and those openings often show up as leaks during the next monsoon. A close inspection of the membrane and parapet flashing is the way to tell.
Will my policy cover water that came down the arroyo into my yard and garage?
Surface water from runoff is generally treated as flood, which standard homeowners policies exclude. Flood coverage comes from the NFIP or a private flood policy, so check whether you carry one.
Does appraisal decide whether my claim is covered?
Appraisal sets the amount of loss, not whether the policy covers it. Coverage disputes are a separate question, and for those you should consult a New Mexico attorney.