Why New Mexico houses are hard to price
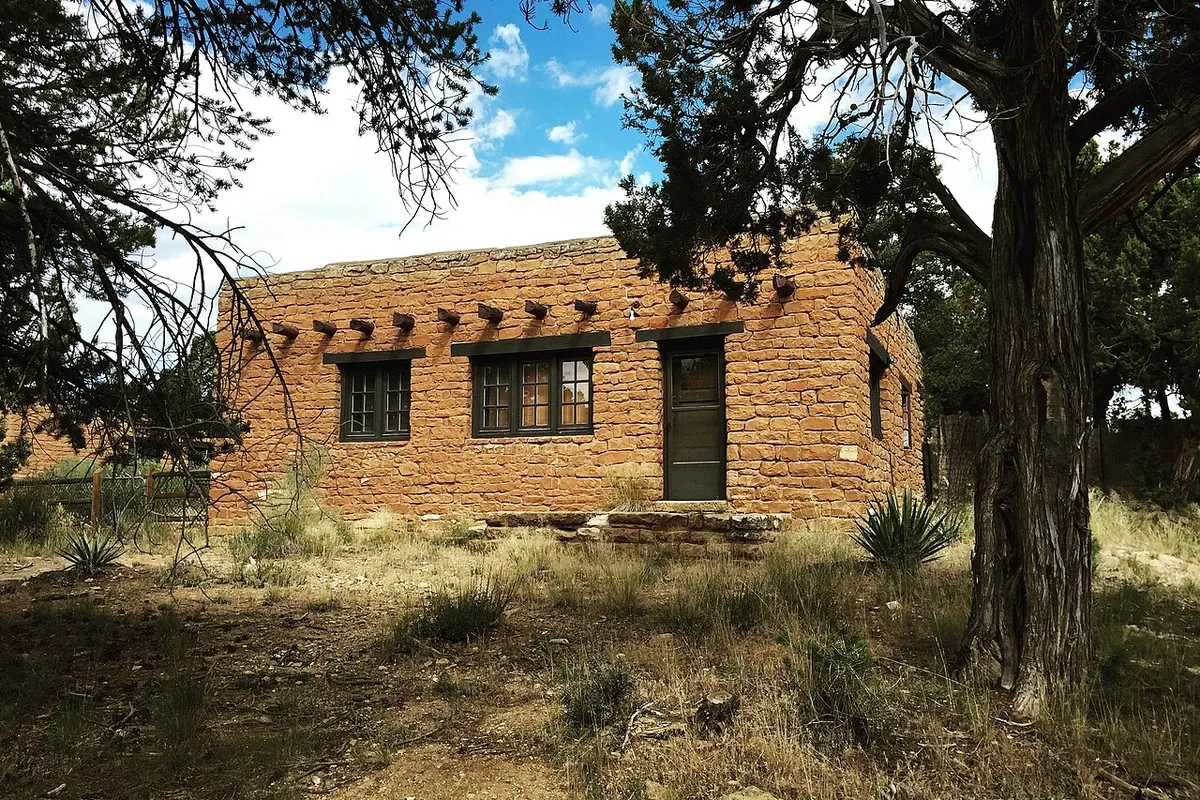
A typical carrier estimate is built from national assumptions. New Mexico homes rarely match them. A Santa Fe adobe with thick mud-plaster walls, a Territorial-style house in Albuquerque with a flat roof and parapets, a newer pitched-roof subdivision in Las Cruces, and a manufactured home on the eastern plains all need different repair methods, crews and materials.
Stucco is the clearest example. Patching a section of a three-coat stucco wall rarely produces an even color and texture match, and the question of how much of an elevation must be refinished often drives the entire dispute. The same goes for hand-troweled interior plaster, viga ceilings and custom tile.
What a home appraisal covers
Under most homeowners policies, the amount of loss can include several coverage parts. We look at each one the policy provides:
- Dwelling. Roof, walls, framing, interior finishes, mechanical systems and built-ins.
- Other structures. Detached garages, casitas, coyote fences, block walls, sheds and portales.
- Personal property. Furniture, clothing, electronics and other contents, valued according to the policy’s replacement-cost or actual-cash-value terms.
- Loss of use. Additional living expense when the house cannot be lived in during repairs, where the policy provides it.
Where homeowners and carriers usually split
On New Mexico homeowners files, disagreements tend to cluster around a handful of issues: repair versus replace on roofs, how far stucco or drywall must be refinished to match, code-required upgrades, the trades needed for the job, depreciation on roofs and contents, and whether general contractor overhead and profit belong in the estimate. Our depreciation holdback splitter shows how replacement cost and actual cash value interact on your payments.
How the process runs
- You send the carrier’s estimate, your policy and any photos or contractor bids.
- We review whether the disagreement is about amount, which appraisal can address, or coverage, which it cannot.
- If appraisal fits and is invoked, we inspect, measure and prepare an independent estimate.
- We work with the carrier’s appraiser and, if needed, an umpire to reach a signed award.
Manufactured and older homes
Manufactured homes are common across New Mexico, from Farmington to Hobbs. Their roofs, skirting and wall panels often require specific parts, and depreciation schedules can be steep. Older adobe and pueblo-style homes raise the opposite problem: materials and craftsmanship that cost more than standard frame construction to reproduce. In both cases, the policy language on matching and valuation matters, so we read it carefully before building a number.
What a New Mexico home insurance appraisal does not do
It does not reopen coverage. If the carrier says a detached studio is excluded or a contents category falls under a sublimit, the panel will not overrule that decision; it prices what is in dispute. A New Mexico home insurance appraisal works best when everyone agrees the loss happened and the only real question is what it costs to put the house back the way it was. Keeping that boundary clear from the first phone call saves time, money and frustration for everyone involved.
Next steps
If your claim is already paid in part and you think the payment is short, a claim estimate review may be the right first step. If the policy’s appraisal clause has already been invoked, see our appraisal clause representation page. Homeowners in Albuquerque, Santa Fe, Las Cruces and across the state can find local details on cities we serve.
Questions about home insurance appraisal
Does appraisal apply to contents as well as the house?
Often yes, if the policy’s appraisal clause applies to the amount of loss generally. Check your form, because some policies treat certain coverages differently.
Will my stucco be matched across the whole wall?
That depends on the policy’s wording and the physical facts. Appraisal can price what a uniform repair requires, but coverage disputes about matching may need legal advice.
Can I still use my own contractor?
Usually yes. The award sets the amount of loss; who performs the repairs is generally your choice unless the policy says otherwise.