One question, answered carefully
New Mexico Insurance Appraiser focuses on the amount of loss. We don’t sell roofs, we don’t argue coverage and we don’t run lawsuits. We measure, document and price damage so that the people deciding a claim — the insurer’s appraiser, an umpire, or the adjuster before it ever gets that far — can see what the repair really costs.
How we work
- Scope before numbers. We inspect and measure before reading anyone else’s estimate.
- Local pricing. Material and labor costs in Farmington, Hobbs and Santa Fe aren’t the same; estimates should reflect where the property is.
- Defensible, not inflated. An estimate that can’t survive an umpire doesn’t help you. We price what we can support.
- Plain English. You’ll understand every difference between our valuation and the insurer’s.
- Fees in writing. You know the cost before any work begins.
Who we work with
Homeowners, landlords, HOA boards, property managers, churches and business owners across New Mexico, as well as the contractors and attorneys who represent them. On any claim we serve in one role only, and we disclose prior relationships with the other appraiser or the umpire.
What we are not
We aren’t a law firm and we don’t give legal advice. We aren’t public adjusters. We don’t guarantee results — no honest appraiser can. If your claim has been denied or a deadline is close, we’ll suggest talking to a New Mexico attorney first.
Built for New Mexico buildings
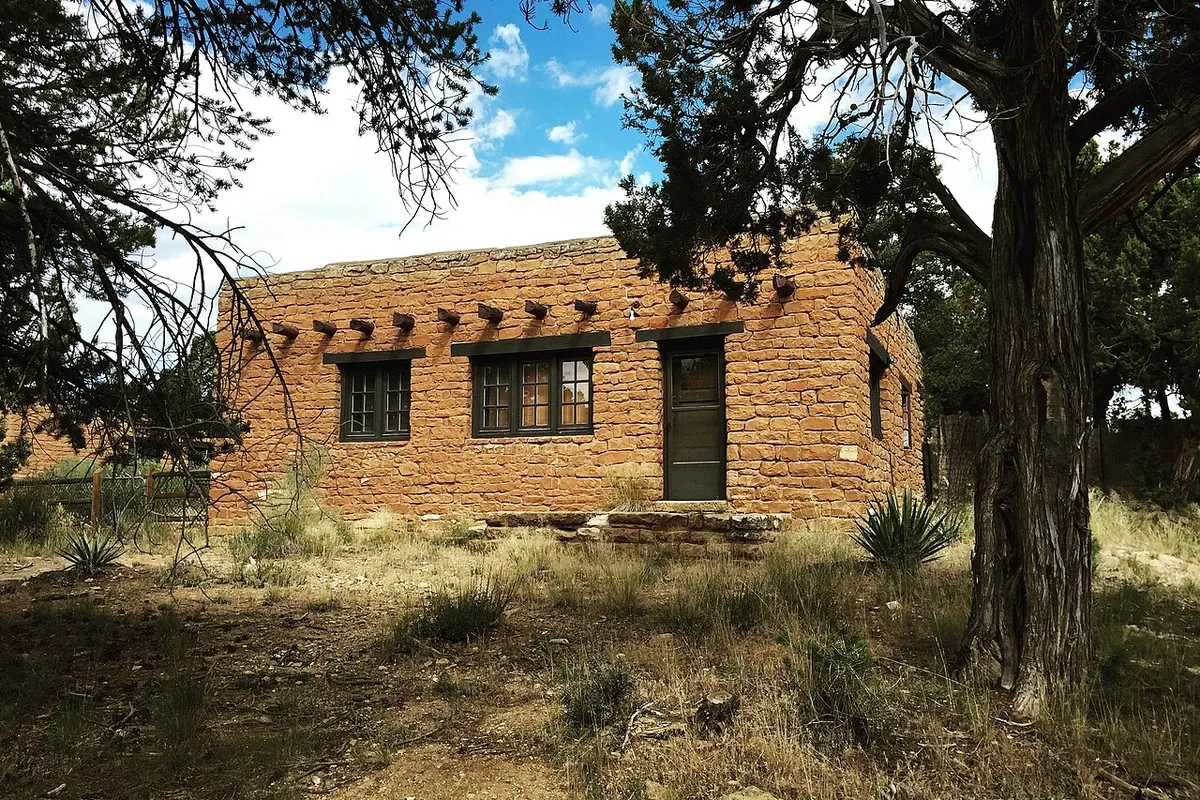
Parapet walls and canales, three-coat stucco, viga ceilings, evaporative coolers, metal mountain roofs and manufactured homes all show up in New Mexico claims, and generic estimates often price them poorly. Knowing how they’re built — and repaired — is most of the job.