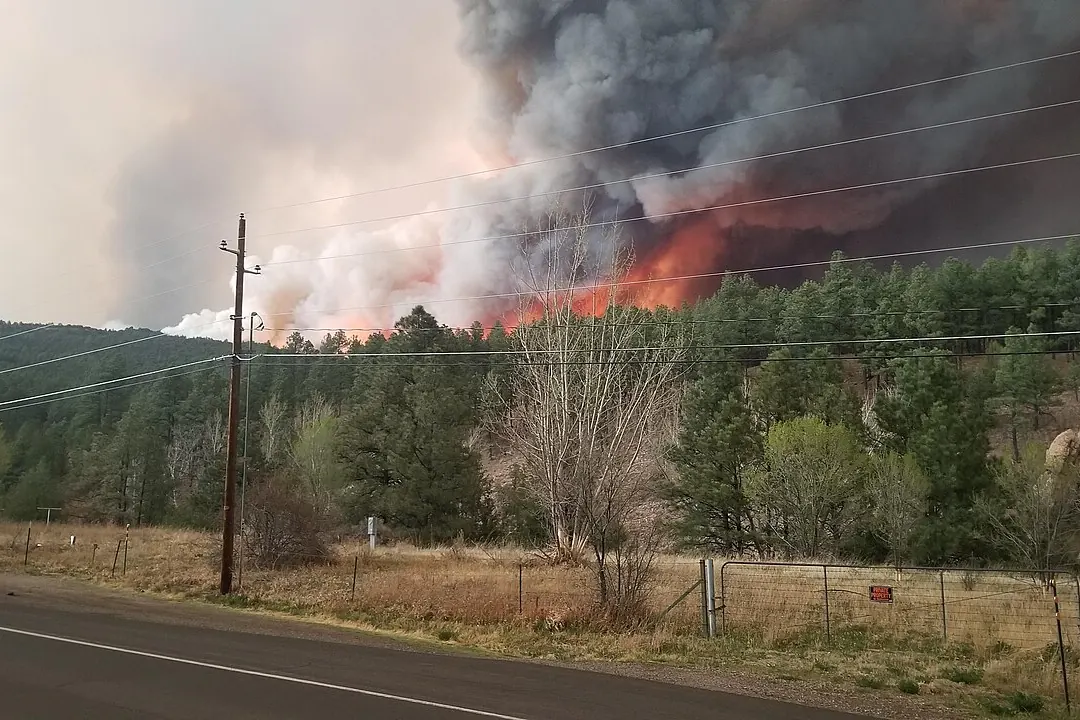
Wildfire in New Mexico
Several of the state’s most destructive fires reached homes directly. The Cerro Grande Fire in May 2000 began as a prescribed burn and destroyed hundreds of homes in Los Alamos. In 2022 the Hermits Peak/Calf Canyon Fire, which grew from two prescribed burns that escaped control, became the largest wildfire in recorded New Mexico history and burned across San Miguel and Mora counties. In June 2024, the South Fork and Salt fires near Ruidoso destroyed or damaged a large number of homes and other structures in the village and surrounding areas.
Each event left owners facing the same questions: what does it cost to rebuild here, now, and how much of what was lost can be documented?
Total losses
When a home burns to the foundation, the dwelling claim often turns on rebuild cost. Carriers may rely on a valuation tool or a per-square-foot figure, while the actual cost to rebuild in a mountain community after a large fire can be considerably higher because of limited crews, longer haul distances, steep lots, updated codes and demand from many owners rebuilding at once.
- Dwelling rebuild cost based on the home’s actual construction: log, frame, stucco, metal roofing, decks and custom finishes.
- Debris removal, which may have its own limit or be an additional amount under the policy.
- Foundation and site work, including whether a fire-exposed slab or footing can be reused.
- Other structures such as garages, barns, fences, wells, septic components and retaining walls.
- Code upgrades where ordinance-or-law coverage applies.
Partial losses and smoke damage
Homes at the edge of a fire may survive with heavy smoke, ash and heat damage. Soot gets into attics, insulation, ductwork and evaporative coolers. Exterior paint and stucco may be scorched, and windows may crack from heat. Carriers sometimes price only a surface cleaning; a careful scope considers testing, HVAC cleaning or replacement, insulation removal and sealing.
Contents inventories
A total loss means rebuilding a household inventory from memory. Policies vary on what documentation is required and whether contents can be settled at a percentage of the limit. Our wildfire contents inventory estimator helps organize items by room and category, and the depreciation holdback splitter shows how replacement cost and actual cash value differ on your payments.
Additional living expense
Rebuilding after a large wildfire often takes longer than the average claim timeline assumes. Additional living expense limits and time periods differ by policy, so we look at realistic local schedules when valuing temporary housing.
How appraisal fits
Appraisal sets the amount of loss where the carrier has accepted the claim but disputes the value. It does not resolve coverage questions, such as whether a limit was adequate or whether a particular endorsement applies. If you believe your claim was handled unfairly, the New Mexico Office of Superintendent of Insurance accepts consumer complaints, and a New Mexico attorney can explain your options.
A New Mexico wildfire insurance appraisal is not a shortcut around the policy’s limits; it is a way to make sure the amount of loss reflects what rebuilding in that specific place really costs.
Where we work
Wildfire risk runs through Ruidoso, Los Alamos, Santa Fe and the mountain communities of northern and central New Mexico. If your claim is stalled, start with the appraisal file checkup or contact us with your policy and the carrier’s estimate.
Questions about wildfire loss appraisal
My home was a total loss. Do I still need an estimate?
Often yes. If the dwelling limit may exceed or fall short of the actual rebuild cost, a detailed estimate helps establish the amount of loss.
Is the federal Hermits Peak/Calf Canyon program part of my insurance claim?
No. It is a separate federal compensation program with its own rules. Ask that office or a New Mexico attorney how it relates to your insurance.
Can smoke damage alone justify a claim?
It can, if the policy covers it and the damage is physical. Testing and documentation help show what cleaning or replacement is needed.