- Wildfire
- Smoke damage
- Snow load
- Frozen pipes
- Post-fire flooding
A mesa community shaped by fire
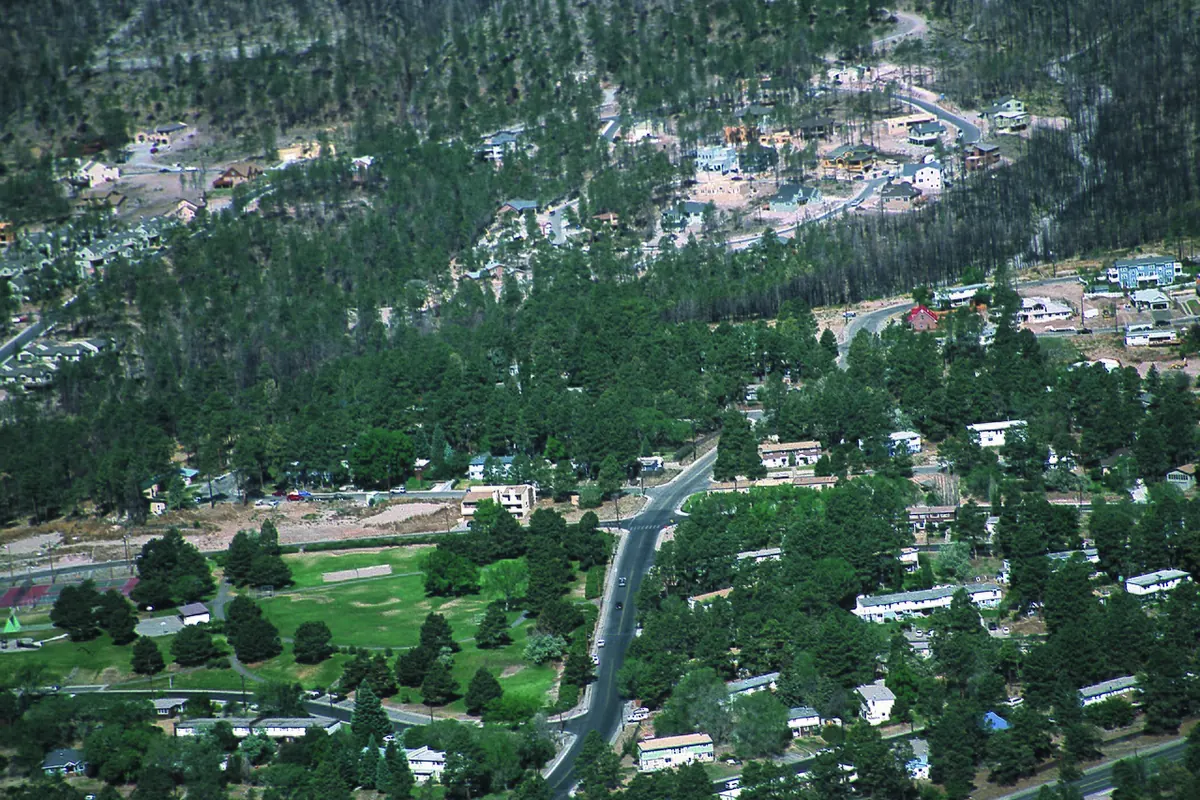
Los Alamos County occupies a series of narrow mesas on the Pajarito Plateau, separated by deep canyons and backed by the Jemez Mountains. The setting is spectacular, and it puts homes directly against forested slopes. In May 2000, the Cerro Grande Fire, which began as a prescribed burn, swept into the townsite and destroyed hundreds of homes. In 2011, the Las Conchas Fire burned through the Jemez Mountains south and west of town, forcing evacuations and closing the laboratory. Both events left lasting marks on the landscape and on how residents approach insurance.
Burn scars change how water moves. After a major fire, heavy summer rains run off scorched slopes faster and carry debris into canyons, raising the risk of flooding below them. That post-fire flood risk is a separate coverage question from wildfire, since standard homeowners policies exclude flood.
Housing in Los Alamos and White Rock
Much of the townsite was built quickly in the mid-twentieth century to house laboratory workers, leaving neighborhoods of modest frame homes, duplexes and apartments, many since expanded and remodeled. Pitched asphalt shingle and metal roofs are common, reflecting the snow. White Rock, a few miles southeast on its own mesa above White Rock Canyon, has more ranch-style homes from later decades and some newer construction. Throughout the county, homes face heavy snow, deep cold and the challenges of building on rock.
Claim disputes we see in Los Alamos County
- Total wildfire losses. Disagreements over dwelling replacement cost, especially when construction costs in a small, remote market run higher than estimating databases show.
- Contents claims. After a total loss, building a contents inventory from memory is overwhelming, and valuation disputes are common.
- Smoke damage. Homes that survive a fire may need extensive cleaning, HVAC work and contents treatment, and the scope is often contested.
- Snow and ice. Roof damage from snow load and ice dams, plus water intrusion that follows.
- Frozen pipes. Bursts during deep cold, particularly in older homes with plumbing in exterior walls.
Our wildfire loss appraisal, fire and smoke damage appraisal and winter freeze appraisal pages explain our approach.
How we help in Los Alamos
We serve Los Alamos and White Rock from our statewide practice, with no local office. For wildfire and smoke claims, we review your policy limits and the carrier’s valuation, inspect what remains, and build an independent estimate of the dwelling, other structures and contents. For winter losses, we focus on documenting the damage and the full cost of repair.
If the parties can’t agree on value, we can be appointed as your appraiser under the policy’s appraisal clause. Read inside the appraisal process, see nearby Santa Fe, or contact us to begin.
Services available in Los Alamos
Every New Mexico Insurance Appraiser service is available in Los Alamos and the rest of Los Alamos County, including:
- Appraisal Clause Representation
- Home Insurance Appraisal
- Commercial & HOA Appraisal
- Hail & Roof Appraisal
- High Wind Damage Appraisal
- Water Damage Appraisal
- Fire & Smoke Damage Appraisal
- Wildfire Loss Appraisal
Los Alamos claim questions
Can appraisal help if my insurer’s replacement cost estimate after a wildfire is too low?
Yes. If the disagreement is about the amount needed to rebuild, appraisal can address it. Whether your policy limits are high enough is a separate issue, and appraisal cannot raise a limit.
Is flooding after a wildfire covered by homeowners insurance?
Flooding and mudflow are generally excluded from standard homeowners policies, even after a fire. Coverage is available separately through the NFIP or private insurers.
Do you serve White Rock as well as the Los Alamos townsite?
Yes. We serve all of Los Alamos County, including White Rock, as part of a statewide practice.